Part buy, part rent
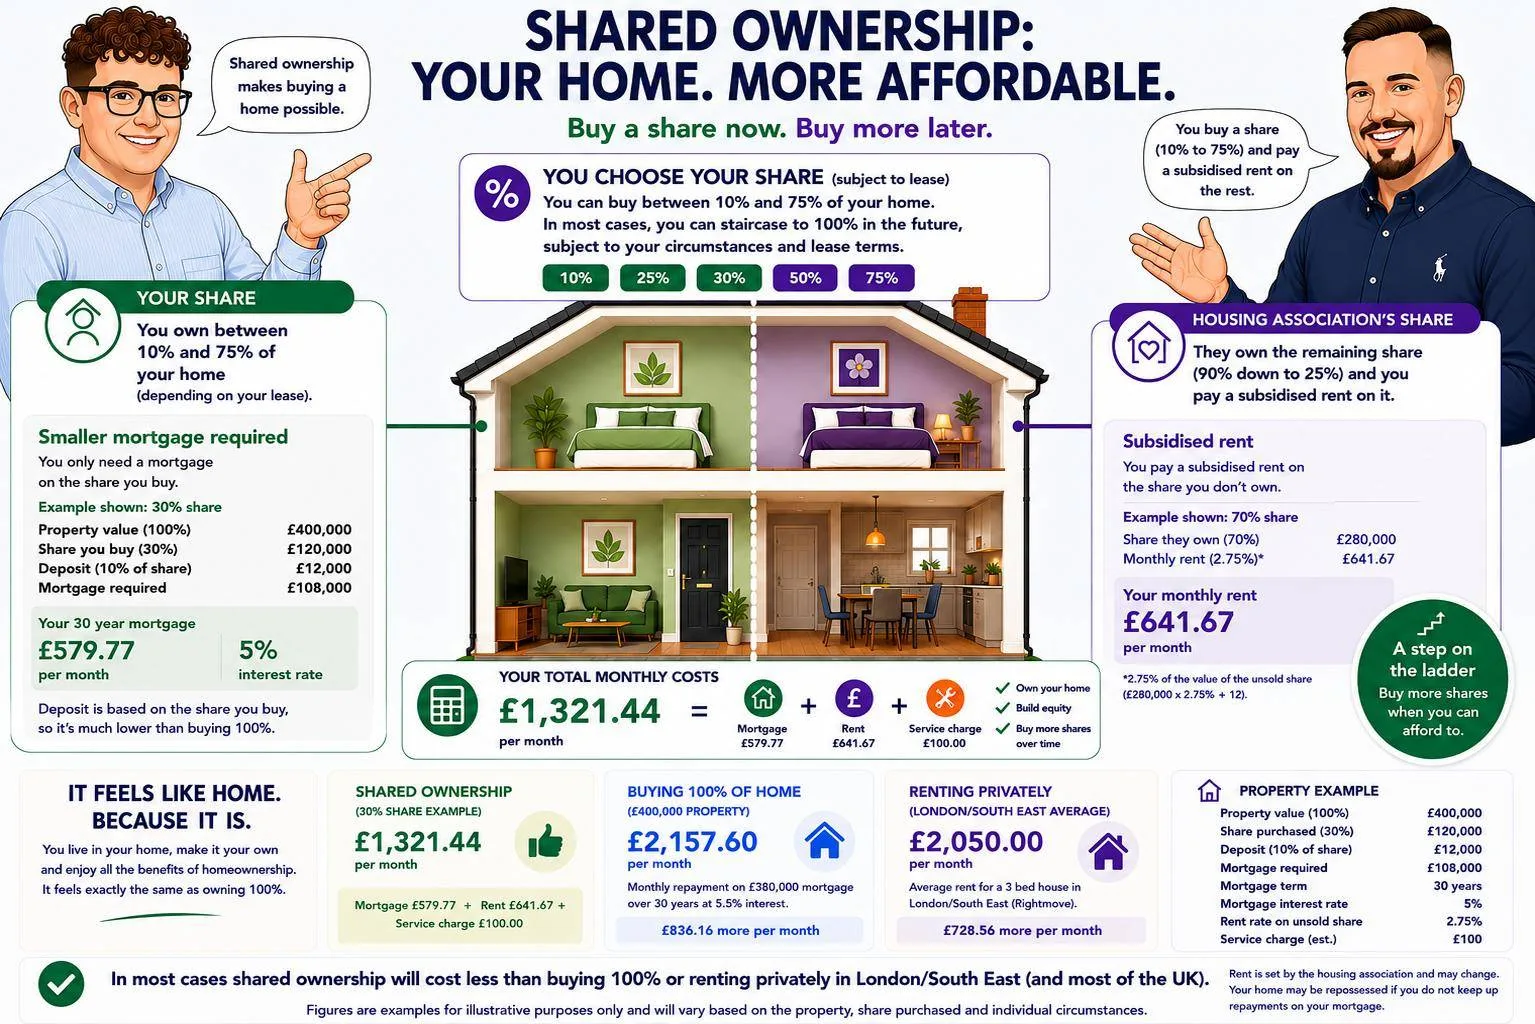
You buy a share of the property and pay rent to the housing provider on the remaining share.

Specialist shared ownership guidance for eligibility, affordability, housing provider checks, mortgage options, and future staircasing plans.
Shared ownership information
Shared ownership can help when buying the whole property is not affordable yet. SRC helps you understand the share, rent, lease, costs, lender criteria, and what buying more later may involve.
You buy a share of the property and pay rent to the housing provider on the remaining share.
Many schemes allow an initial share between 10% and 75%, depending on the property and provider.
Your budget needs to include mortgage payment, rent, service charges, ground rent where relevant, and protection costs.
You may be able to buy more shares later. As your owned share rises, rent on the provider share usually reduces.
Eligibility guidance
Eligibility is not only about income. Housing providers and lenders may also look at buyer status, location rules, affordability, deposit, commitments, and whether the property meets your needs.
Start financial assessmentCurrent public guidance includes these headline checks.
These figures are set by government and can change. Last reviewed .
Review income, buyer status, local connection, and property search area.
Combine mortgage, deposit, rent, service charge, and household spending.
Get documents ready for the housing provider, broker, and lender.
Financial assessment information
A shared ownership application usually has two conversations running together: housing provider assessment and mortgage lender underwriting.
Photo ID, proof of address, right to reside evidence where needed, and current housing position.
Payslips, accounts, tax calculations, benefits, overtime, bonuses, or contract details.
Loans, cards, childcare, travel, maintenance, rent, bills, and expected service charges.
Recent credit conduct, registered address history, deposit source, and lender criteria points.
Things to be aware of
Shared ownership works differently from a standard purchase, and much of the detail sits in the lease for the specific home. These are the points that most often affect cost, mortgage choice, and selling later.
Rent on the housing provider share can increase over time, in accordance with the terms of your lease.
Service charges are reviewed periodically and can change from one year to the next.
Your lease sets out repair and maintenance obligations, which usually sit with you as the shared owner.
Meeting the scheme eligibility rules does not guarantee that a lender will approve a mortgage.
The number of years remaining on the lease can affect which lenders will consider the property.
Construction type and building safety requirements may affect whether a mortgage is available.
Resale and nomination provisions differ between leases, so the process for selling can vary.
FAQs
These answers are a starting point. Your adviser will check the provider rules, lender criteria, and lease details for the specific home you want.
Deposits are usually based on the share you buy, not the full property value. The exact amount depends on the lender, property, and your circumstances.
Eligibility normally considers household income, affordability, buyer status, and whether you can buy a suitable home without the scheme. Some properties add local connection rules.
Staircasing means buying more shares in the property later. This can reduce the rent paid on the provider-owned share.
Yes. Lenders and housing providers normally look at the combined monthly cost, including mortgage, rent, service charge, and other commitments.
Yes, but the lease and housing provider process matter. Resale rules can differ, so it is worth checking the terms early.
The assessment checks income, outgoings, deposit, credit profile, and whether the property costs remain affordable after completion.
External resources
Official guide to buying, costs, rent, staircasing, selling, and help.
Visit resourceCurrent eligibility rules, income limits, buyer status, and local connection notes.
Visit resourceOverview of government-backed routes that may help with buying a home.
Visit resourceShared ownership property search and practical buyer resources.
Visit resourceWe use essential cookies to make this website work and to keep our forms secure. We would also like to load our live chat, which is provided by tawk.to and sets its own cookies. If you reject, the live chat will not be available — everything else on the site works exactly the same, and you can still call or email us. We do not use advertising or analytics cookies, and we do not track you across other websites. Read our Cookie Policy.
You can change your choice at any time.
Our live chat is provided by tawk.to and needs its cookies. Accept below to start chatting, or call us on 01268 280096 instead.